Examining Monetary Transaction Sequences in Fusion Digital Recreation Systems Serving UK Consumers
Iris Wolf · Jun 19, 2026
Examining Monetary Transaction Sequences in Fusion Digital Recreation Systems Serving UK Consumers
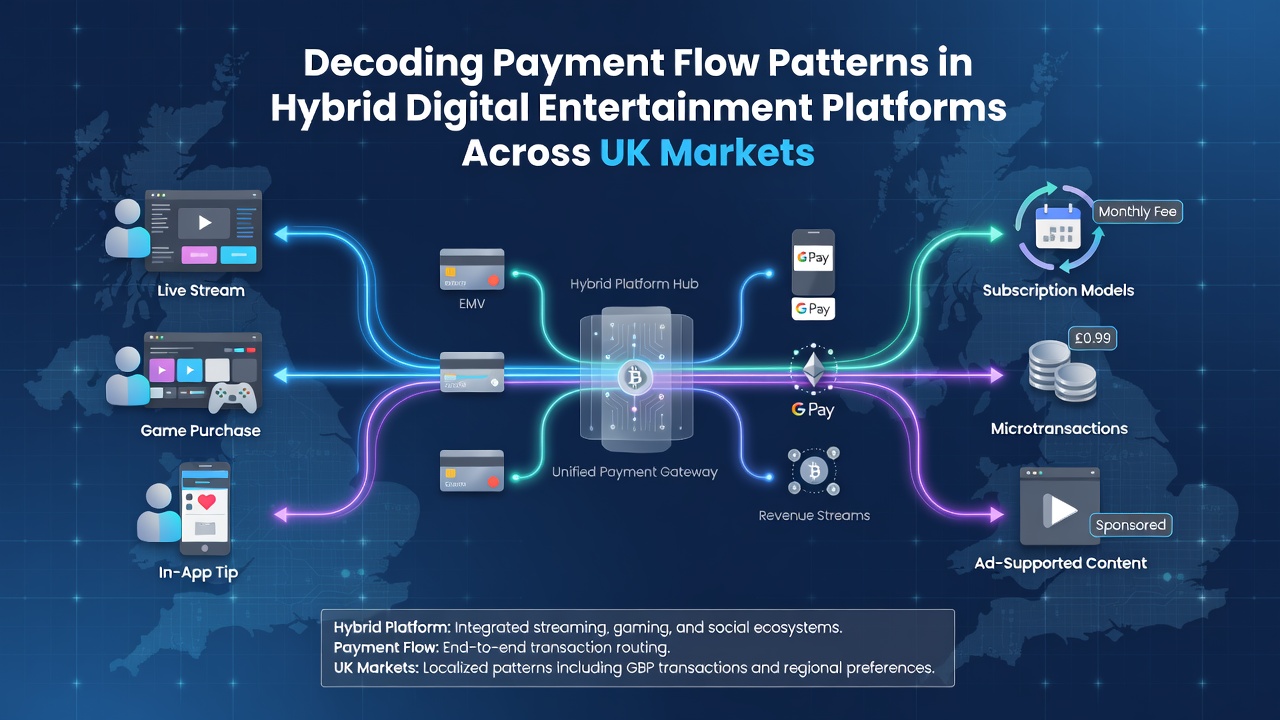
Hybrid digital entertainment platforms combine elements of gaming, betting, and interactive media into unified user experiences that require seamless payment integration, and analysts tracking these systems across UK markets have documented distinct patterns in how funds move through deposits, in-game purchases, and withdrawals over recent years.
Core Components of Payment Infrastructure
These platforms rely on layered payment rails that include traditional card networks alongside instant bank transfers and digital wallets, while data compiled through industry monitoring reveals that transaction volumes often spike during evening hours and weekends when user engagement peaks in multiple regions simultaneously. Observers note that open banking protocols have accelerated processing times since their wider adoption, allowing funds to clear in seconds rather than days, and this shift has altered the rhythm of both incoming and outgoing cash movements.
Security layers such as tokenization and real-time verification sit at the foundation of these flows, yet patterns emerge where users in urban centers tend to favor mobile-initiated transfers compared with slower adoption rates observed in rural areas. Figures reveal that average deposit sizes fluctuate seasonally, with increases tied to major sporting events and promotional periods that encourage higher activity levels across the networks.
Regional Variations and Timing Trends
Payment behaviors differ notably between England, Scotland, Wales, and Northern Ireland, with northern markets showing stronger preference for direct debit setups that support recurring small transactions, whereas southern regions demonstrate higher volumes routed through international card schemes. Researchers have tracked these differences through aggregated anonymized datasets that highlight how time zones and local economic factors influence when funds enter and exit the platforms.
By June 2026 projections indicate further integration of AI-driven fraud detection that could reroute suspicious flows automatically, and early implementations already show reduced reversal rates in test environments. Such developments connect directly to broader European payment harmonization efforts that continue to shape how hybrid platforms manage cross-border elements even within domestic UK operations.
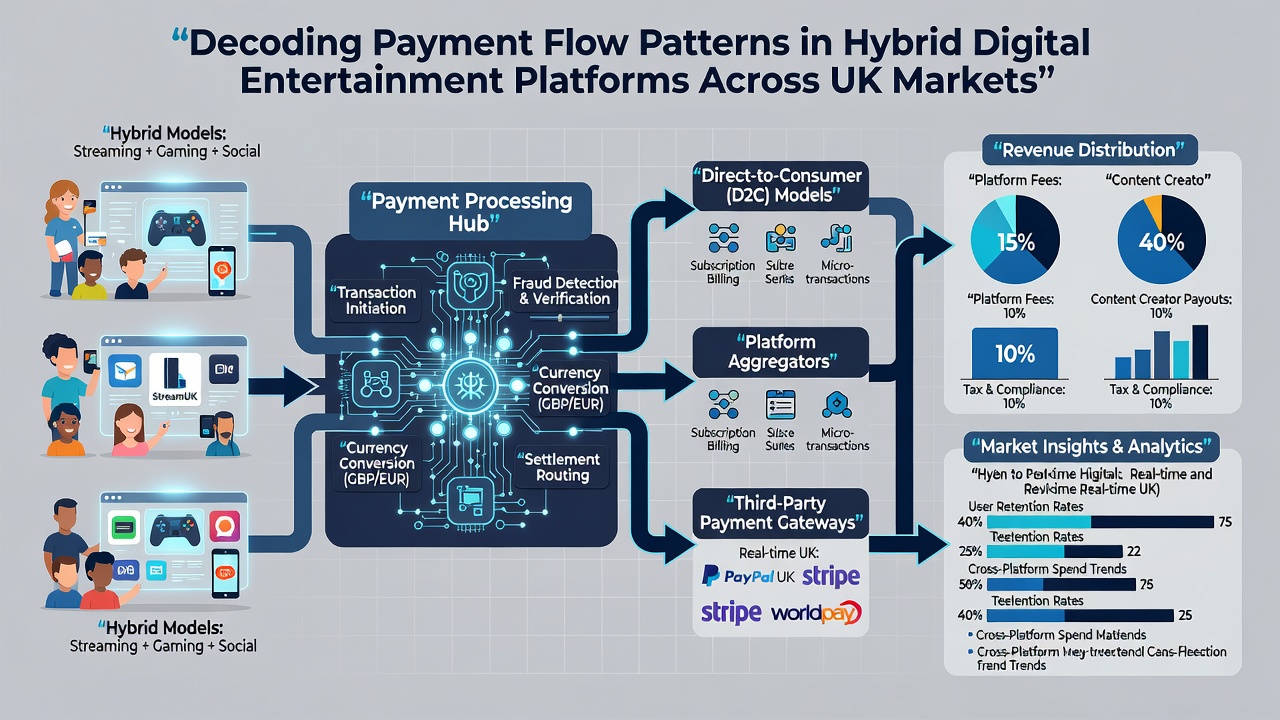
What's interesting here is the way micro-transactions for in-platform features create steady trickles of activity between larger deposit events, smoothing overall cash movement and reducing volatility that once characterized these systems. Data from multiple monitoring sources shows this pattern stabilizing user balances while increasing the total number of individual transfers processed daily.
Influences from Regulatory and Technological Shifts
Adjustments in consumer protection rules have prompted platforms to implement clearer disclosure mechanisms around fees and processing durations, leading to more predictable outflow patterns as users plan withdrawals with greater awareness. Industry reports indicate that adoption of instant payment schemes has grown steadily, cutting average settlement times and altering weekend processing dynamics that previously relied on batch systems.
Take one analysis from the European Central Bank that examined instant payment adoption rates across member states, noting parallels with UK market behaviors where faster rails correlate with higher repeat transaction frequency. Meanwhile a separate study conducted through OECD channels on digital payment inclusion highlights how access disparities in certain demographics affect overall flow distribution within entertainment ecosystems.
Hybrid platforms must balance these external pressures with internal optimization that routes payments through the most cost-effective channels available at any given moment, and evidence suggests successful implementations achieve this through dynamic switching algorithms rather than static preferences.
Future Trajectory and System Adaptations
Looking ahead, continued refinement of these payment sequences depends on how platforms incorporate emerging technologies such as programmable money features and enhanced data analytics that could predict user funding needs before they arise. Patterns observed so far point toward greater fragmentation of payment types within single sessions, where users switch methods mid-interaction based on available incentives or speed requirements.
Those who've studied transaction logs across multiple operators report that loyalty-linked payment bonuses have begun influencing choice architecture, steering flows toward specific rails that offer mutual benefits to both users and platform operators. This creates feedback loops where certain methods gain dominance in particular user segments over time.
Conclusion
The interplay between technology, regional habits, and external regulatory frameworks continues to reshape how monetary sequences unfold within these hybrid systems, producing increasingly sophisticated patterns that reflect both user preferences and operational efficiencies. Monitoring these developments provides ongoing insight into the evolving financial backbone supporting digital entertainment across UK markets, with June 2026 expected to mark further milestones in processing speed and security integration.